Picture an insurance company. Pricing for its health products relies mainly on static information — medical history, age, lifestyle questionnaires filled out once and rarely updated, even as a policyholder's actual health changes over the years. Pricing stays behind reality, either priced conservatively due to insufficient information, or dependent on self-reported data that's hard to verify.
What the company wants is pricing that reflects someone's real, ongoing health status, not a form filled out years ago.
The obstacle is that continuous health data tends to be fragmented — coming from different devices in different formats, hard to feed directly into existing risk models, let alone update dynamically.
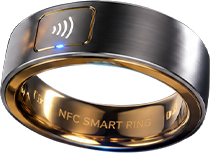
Anvor provides a continuous stream of health data that can feed into risk models, not a pricing conclusion meant to replace actuarial judgment. With explicit user authorization, heart rate and activity data flow into the insurer's own risk assessment framework as one input for dynamic pricing exploration — whether to use it, how to weight it, and the final pricing logic all remain entirely with the insurer's own models and actuarial team. The data only becomes more continuous and more current; the judgment stays with people.
Equally important is the other side of this: sharing data is a choice, not a condition of coverage. Declining doesn't affect basic coverage. For those who opt in, it offers something a form filled out years ago never could.
Risk assessment was never really about whether to look at someone's health. It's about whether what's being looked at is current enough to be true.